Debt Consolidation
Can I Combine My Credit Card and Online Loan App Debts Into One Monthly Payment?
If you are juggling a credit card bill, one or more online loan apps, and maybe a few other debts, all with different due dates and sky-high interest, you have probably wondered if there is a way to just turn them into one payment. The answer is yes. It is called debt consolidation, and it is one of the most effective ways to get a tangled debt situation back under control.
This guide explains how combining your debts works, how to do it, and what to watch for. Simple language, made for regular working people.
💡 Highlights
- Yes, you can combine your credit card, online loan apps, and other debts into one monthly payment.
- This is called debt consolidation, and it replaces many due dates with a single one.
- Done right, it can lower your total interest and give you a longer, more affordable term.
- You can consolidate through a bank loan, a balance transfer, the IDRP for cards, or a consolidation service.
- Bank loans need good credit and income, which is hard if you are already behind.
- A consolidation service can combine your debts even when a new bank loan is out of reach.
- Combining debts does not erase them, so the goal is one payment you can actually afford.
Can You Really Combine Different Types of Debt?
Yes, you can. Debt consolidation is built for exactly this. It takes several separate debts, like your credit card balance and your loan app balances, and combines them into one single obligation with one monthly payment. Instead of tracking five due dates and five interest rates, you track one.
It works even when your debts come from very different places. A credit card, an online lending app, a salary loan, and a buy-now-pay-later balance can all be rolled together. The point is not the type of debt, but bringing them into one manageable plan.
Why Would You Want to Combine Them?
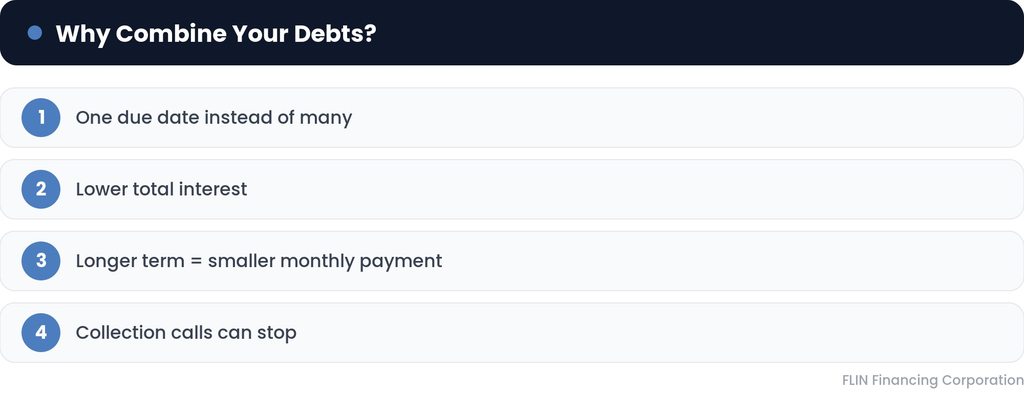
Because scattered, high-interest debt is hard to manage and expensive. When you combine your debts, a few good things happen at once.
First, your life gets simpler, with one due date and one payment instead of many, which makes it far easier to avoid missed payments. Second, your total interest can drop, especially since online loan apps and credit cards carry some of the highest rates around. Third, spreading the balance over a longer term can lower your monthly payment, which frees up room in your budget. And fourth, it can stop the constant collection calls once your debts are settled into one plan.
How Can You Combine Your Debts?
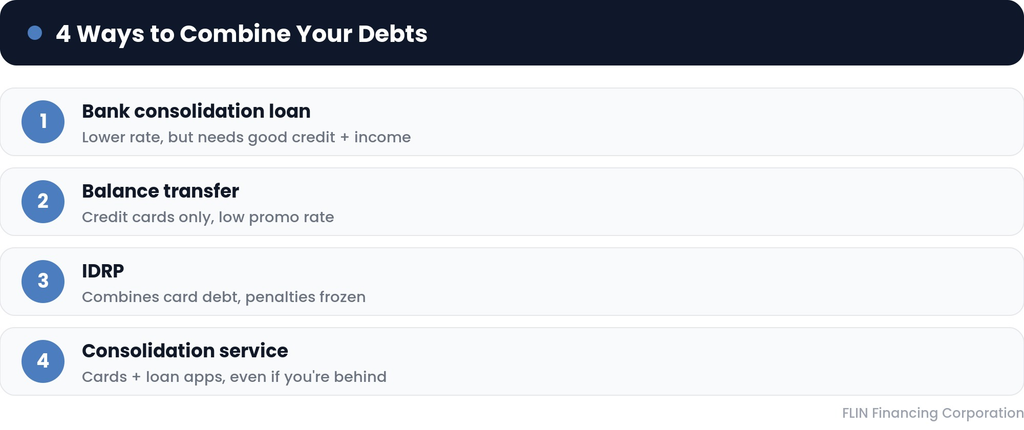
There are a few ways to do it, and the right one depends on your situation.
A bank consolidation loan
You take one personal loan big enough to pay off your card and loan apps, then repay just that loan. As Philippine legal guidance explains, this usually means a lower interest rate than credit cards, which sit around 3 percent per month. The catch is that banks require decent credit and stable income, so this works best if you are stretched but still in good standing.
A balance transfer
If the debt is mostly on credit cards, you can move the balances onto one card with a low promotional rate. This helps with cards but does not cover loan apps.
The Interbank Debt Relief Program (IDRP)
As legal guidance describes, this combines credit card debts from different banks into one plan at a reduced rate with penalties frozen. It is for credit cards specifically, not loan apps.
A debt consolidation service
Instead of you qualifying for a new loan, a service combines your existing debts into one restructured plan and pays your creditors directly. This can cover both your credit cards and your loan apps, and it can work even if your credit has already taken a hit.
What if You Cannot Qualify for a Bank Loan?
This is the most common problem, so it is worth addressing directly. The frustrating part of bank consolidation is that the deeper in debt you are, the harder it is to qualify. If you have already missed payments or your debts take up most of your income, a bank may turn you down, which is exactly when you need help most.
If that is your situation, you are not out of options. A consolidation service works with the debt you already have, rather than depending on a new loan approval. It brings your credit card and loan app balances into one plan and handles the payments to your creditors, so you deal with one party instead of many. This is often the realistic path for people who are already behind.
What Should You Watch For?
A few things keep consolidation safe and worthwhile. Make sure any lender or service you use is properly SEC licensed and registered. Compare the total cost and the full term, not just the monthly payment, because stretching the term too long can raise the total interest you pay. And most important, once your debts are combined, do not run the balances back up, since the whole point is to get out, not to make room to borrow more.
One note: this article is general information, not legal or financial advice. For a complex situation, free legal help is available from the Public Attorney’s Office if you qualify.
Combining Your Debts the Simple Way
If your credit card and loan app balances have become a tangle of due dates you can barely keep up with, combining them into one payment is often the clearest way forward, and you do not have to arrange it all alone.
FLIN helps salaried Filipinos combine high-interest debts, credit cards, online loans, and buy-now-pay-later balances, into one more manageable monthly payment. Because it works with your existing debts, it can help even when a regular bank loan is not an option. A short, no-pressure consultation is enough to see what fits your situation. Turning many stressful payments into one you can actually handle is very possible, and it often starts with a single conversation.
Find out more about how to make your debt become simpler via articles below:
Your Debt-Free Life Start Here
Consult with us and get the best solution based on your financial condition
SEC Registered
SEC Registration number : 2026040247321-01